Datenbankbereich · 165 Unternehmen
Unternehmen
Jede Schicht des Ökosystems — Designer, Foundries, Speicher, Ausrüstung, Server, Netzwerk, Strom, Kühlung, Rechenzentren, Clouds, Labs und das dahinterstehende Kapital.
Feldnotizen
Hundertfünfundsechzig Unternehmen, und fast jedes ist ein Engpass, über den sich irgendjemand sorgt. Stöbern Sie nach Schicht, und beachten Sie, wie oft die Antwort auf „Wer sonst stellt das her?" niemand lautet – diese Konzentration ist die wichtigste Tatsache über diese Branche.
Mit diesen drei beginnen
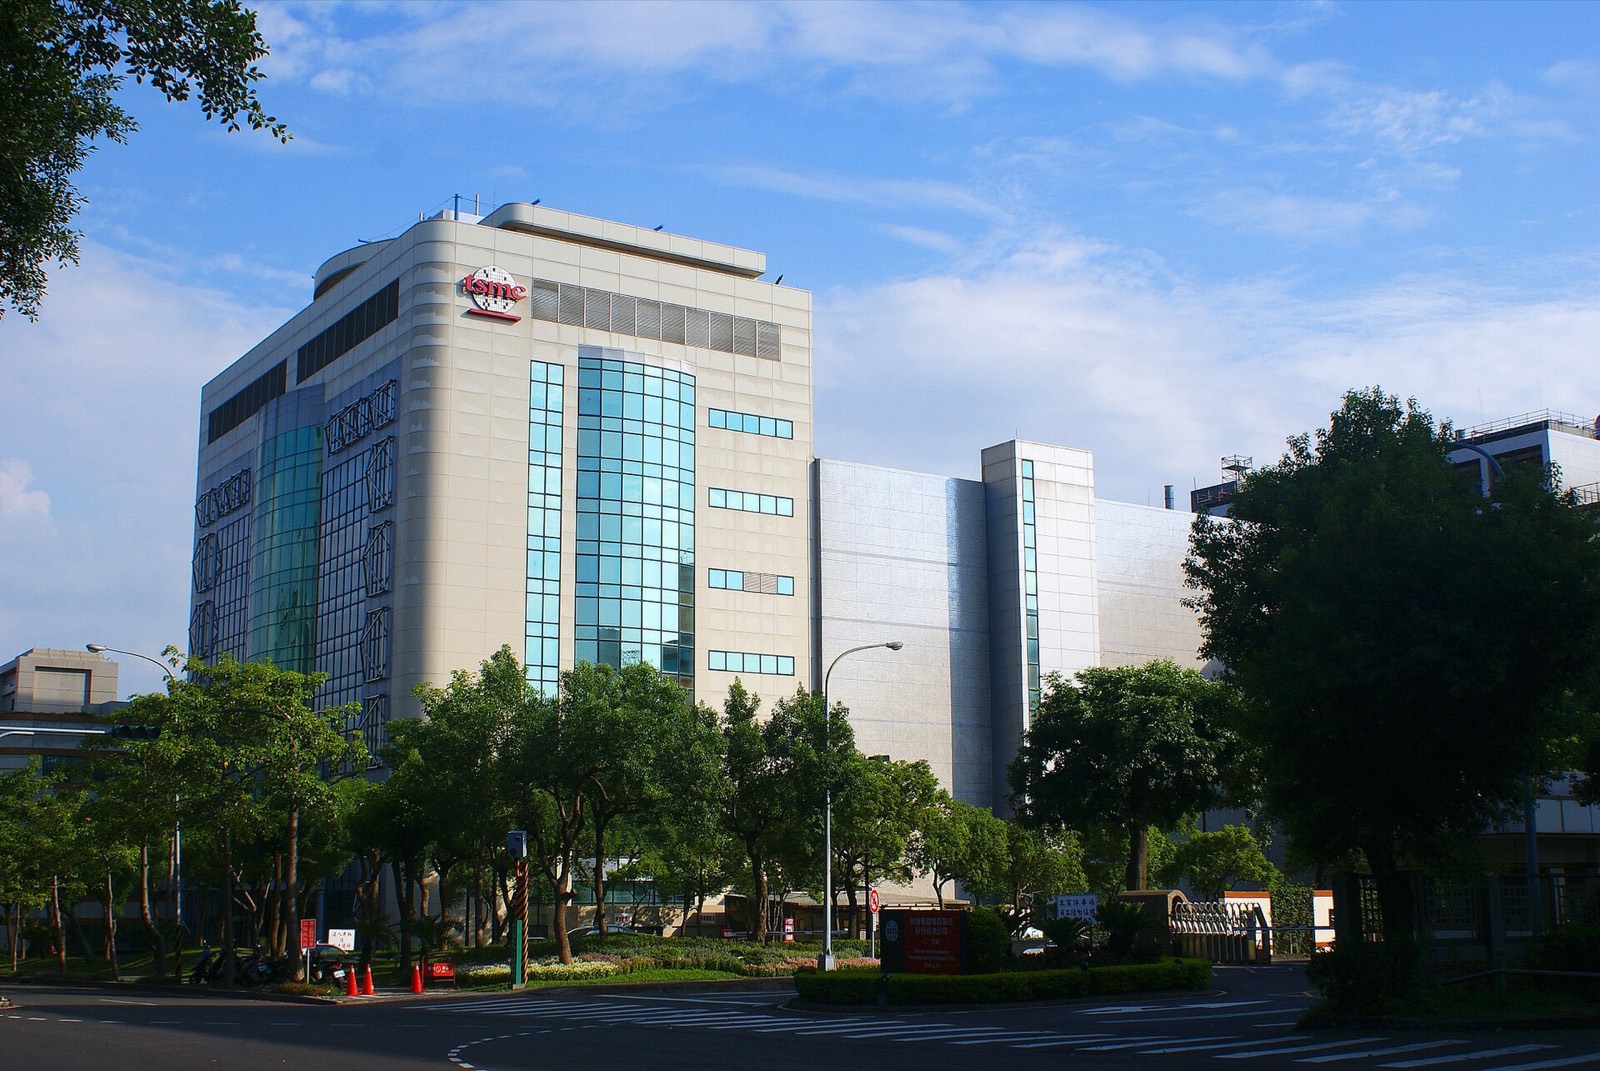 TSMC
Wo fast alles auf dieser Seite physisch hergestellt wird.
 ASML
Ein echtes Monopol ganz unten im Stack.
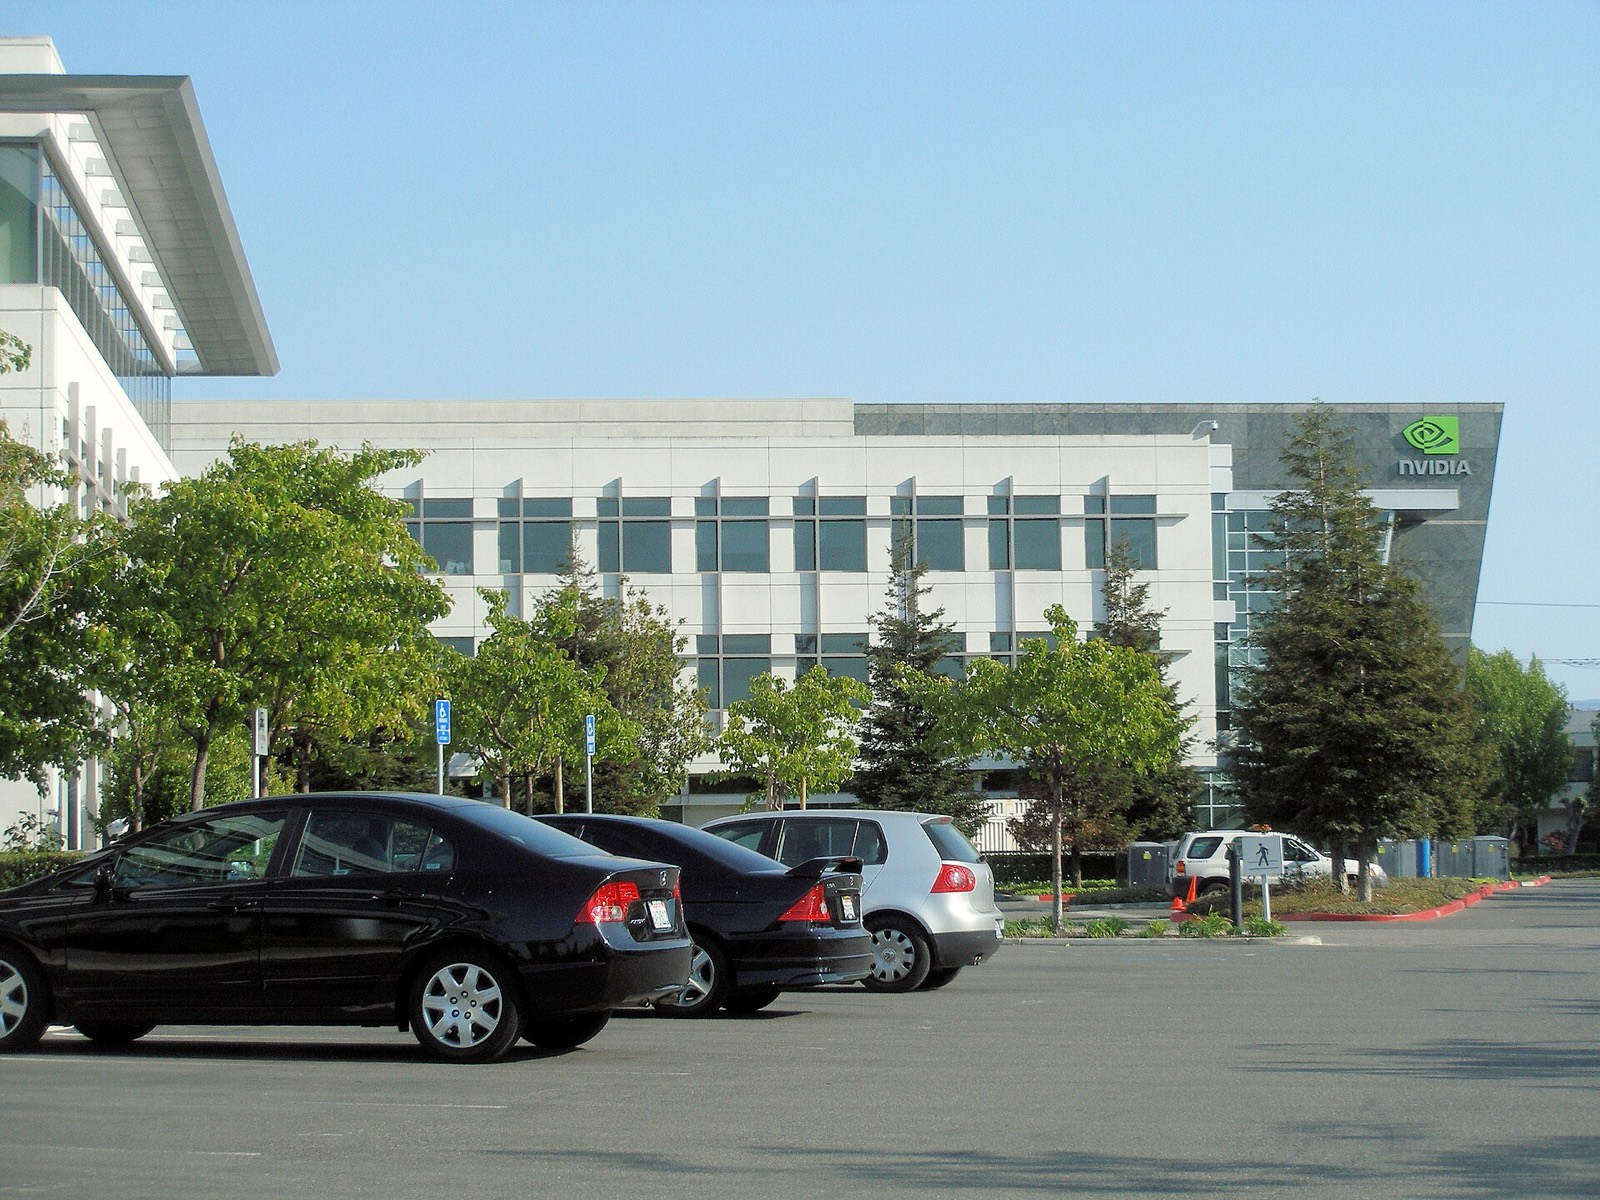 NVIDIA
Das Unternehmen, in dem der gesamte Ausbau denominiert ist.
Chip-Designer & Halbleiter
18 AMDThe credible second source: Instinct GPUs, EPYC CPUs and the ROCm stack.
BT
Biren TechnologyShanghai GPU designer rebuilt around export-compliant parts.
 BroadcomThe quiet giant of custom AI silicon and the switch chips inside every fabric.
CT
Cambricon TechnologiesChina's listed AI-chip champion and prime NVIDIA-substitution play.
CS
Cerebras SystemsThe wafer-scale company: one chip per wafer, sold as systems and cloud tokens.
ET
EtchedThe startup betting silicon permanence on the transformer architecture.
FU
FuriosaAIKorean inference-chip designer that reportedly turned down Meta.
GR
GraphcoreThe UK's IPU pioneer, now SoftBank's AI-silicon arm.
GR
GroqDeterministic inference hardware from the engineer who started Google's TPU.
HU
HuaweiChina's sanctioned giant: Ascend chips, CloudMatrix systems, CANN software.
 IntelThe fallen incumbent betting everything on its 18A process and foundry turnaround.
 MarvellCustom AI silicon and the electro-optics that carry data between racks.
NV
NVIDIAThe company the AI build-out is denominated in: GPUs, systems, networking and CUDA.
 QualcommThe mobile-silicon giant re-entering the data center for inference.
RE
RebellionsKorea's merged national AI-chip champion, fabbed by Samsung.
SS
SambaNova SystemsFull-stack AI systems built around a reconfigurable dataflow architecture.
TE
TenstorrentJim Keller's open-source RISC-V AI company — chips, cards and licensable IP.
DM
d-MatrixIn-memory compute for the economics of small-batch inference.
Foundry & Packaging
5 ASE TechnologyThe world's largest packaging and test house (OSAT).
AT
Amkor TechnologyThe US-headquartered OSAT building advanced packaging in Arizona.
GL
GlobalFoundriesThe trailing-edge specialist that still fabricates Groq's LPU.
SM
SMICChina's leading foundry, pushing 7 nm-class production without EUV.
TS
TSMCThe indispensable factory: nearly every leading AI chip is made here.
Arbeitsspeicher
3 Micron TechnologyAmerica's memory maker, sold out of HBM generations in advance.
 SK hynixThe HBM leader — NVIDIA's primary memory supplier through the boom.
 Samsung ElectronicsMemory giant and foundry challenger, fighting back for HBM share.
Halbleiterausrüstung
7
AS
ASMLThe only maker of EUV lithography machines — a literal monopoly at the source.
AM
Applied MaterialsThe broadest toolmaker: deposition, etch, implant — and packaging tools too.
BS
BE Semiconductor (Besi)The hybrid-bonding specialist for the 3D-stacking era.
DC
DISCO CorporationThe company that cuts and grinds nearly every advanced chip.
KL
KLAProcess control: the inspection tools that make advanced yields possible.
LR
Lam ResearchEtch and deposition leader — critical to HBM's through-silicon vias.
TE
Tokyo ElectronJapan's equipment giant — coaters, etchers and bonders in every fab.
EDA & IP
3
AR
ArmThe instruction set of the AI data center's CPUs — licensed, not manufactured.
 Cadence Design SystemsThe other EDA duopolist — and a growing seller of AI-accelerated design.
 SynopsysThe largest chip-design software company — every AI chip is designed in EDA.
Cadence Design SystemsThe other EDA duopolist — and a growing seller of AI-accelerated design.
SynopsysThe largest chip-design software company — every AI chip is designed in EDA.
Server & Hardware
9
CE
CelesticaThe Canadian EMS firm riding hyperscaler networking and AI systems.
 Dell TechnologiesThe enterprise heavyweight whose XE9680 line became an AI-server franchise.
 Foxconn (Hon Hai)The iPhone assembler that quietly became the largest AI-server builder.
 Hewlett Packard EnterpriseSupercomputing pedigree (Cray) plus the Juniper networking acquisition.
JA
JabilUS manufacturing scale for servers, photonics and liquid-cooling hardware.
 LenovoThe global #3 server maker with a strong liquid-cooling line (Neptune).
QC
Quanta ComputerThe hyperscalers' original ODM — racks straight to Meta, Google and AWS.
SU
SupermicroThe fastest mover in GPU servers — first to market with each NVIDIA generation.
WI
WiwynnThe pure-play hyperscale ODM spun out of Wistron.
Dell TechnologiesThe enterprise heavyweight whose XE9680 line became an AI-server franchise.
Foxconn (Hon Hai)The iPhone assembler that quietly became the largest AI-server builder.
Hewlett Packard EnterpriseSupercomputing pedigree (Cray) plus the Juniper networking acquisition.
JA
JabilUS manufacturing scale for servers, photonics and liquid-cooling hardware.
LenovoThe global #3 server maker with a strong liquid-cooling line (Neptune).
QC
Quanta ComputerThe hyperscalers' original ODM — racks straight to Meta, Google and AWS.
SU
SupermicroThe fastest mover in GPU servers — first to market with each NVIDIA generation.
WI
WiwynnThe pure-play hyperscale ODM spun out of Wistron.
Netzwerk
14
AM
AmphenolConnectors and cable assemblies in every server, switch and rack.
AN
Arista NetworksThe Ethernet switch leader of the AI back-end network.
AL
Astera LabsPCIe retimers and CXL connectivity inside nearly every AI server.
CA
Celestial AIThe Photonic Fabric: optical links from any chip to any memory.
CI
CienaCoherent optics linking AI data centers across cities and oceans.
 CiscoThe networking incumbent pushing its own silicon into AI fabrics.
CO
CoherentOne of the largest makers of the optical transceivers AI clusters consume by the million.
CO
CorningThe fiber-optic cable itself — glass demand doubled by AI campuses.
CT
Credo TechnologyActive electrical cables — the copper that wires racks together.
FA
FabrinetThe contract manufacturer behind NVIDIA's optical transceivers.
LI
LightmatterPhotonic interconnect — moving light into the chip package itself.
LU
LumentumLasers and photonics for the optical layer of AI networks.
 NokiaOptical transport and data-center routing — with NVIDIA as a 2025 investor.
TC
TE ConnectivityThe other connector giant wiring AI racks and power paths.
CiscoThe networking incumbent pushing its own silicon into AI fabrics.
CO
CoherentOne of the largest makers of the optical transceivers AI clusters consume by the million.
CO
CorningThe fiber-optic cable itself — glass demand doubled by AI campuses.
CT
Credo TechnologyActive electrical cables — the copper that wires racks together.
FA
FabrinetThe contract manufacturer behind NVIDIA's optical transceivers.
LI
LightmatterPhotonic interconnect — moving light into the chip package itself.
LU
LumentumLasers and photonics for the optical layer of AI networks.
NokiaOptical transport and data-center routing — with NVIDIA as a 2025 investor.
TC
TE ConnectivityThe other connector giant wiring AI racks and power paths.
Strom & Elektrik
16
AB
ABBSwiss electrification giant supplying medium-voltage gear to hyperscale sites.
BE
Bloom EnergyFuel cells as bridge power for grid-constrained AI sites.
 CaterpillarGensets and gas engines — plus the machines digging the sites.
 CumminsBackup generators — every hall's insurance policy.
DE
Delta ElectronicsPower supplies and cooling for a huge share of the world's AI racks.
EA
EatonSwitchgear, UPS and busway — the electrical spine of every data hall.
GV
GE VernovaAmerica's turbine and grid champion — sold out of gas turbines into the 2030s.
HE
Hitachi EnergyThe world's largest transformer maker — the grid's longest lead-time item.
 InfineonPower semiconductors from grid to GPU — partner on NVIDIA's 800V architecture.
MH
Mitsubishi Heavy IndustriesThe third member of the gas-turbine oligopoly feeding AI campuses.
MP
Monolithic Power SystemsThe voltage regulators feeding each GPU its thousand amps.
NS
Navitas SemiconductorGaN power chips named into NVIDIA's next-gen power designs.
 Rolls-RoyceBackup power today, small modular reactors tomorrow.
SE
Schneider ElectricPower distribution plus cooling (Motivair) — a full data-center electrical stack.
SE
Siemens EnergyGas turbines and grid equipment — order books stretched by AI power demand.
ON
onsemiSilicon-carbide and power chips pushing into data-center supply units.
CaterpillarGensets and gas engines — plus the machines digging the sites.
CumminsBackup generators — every hall's insurance policy.
DE
Delta ElectronicsPower supplies and cooling for a huge share of the world's AI racks.
EA
EatonSwitchgear, UPS and busway — the electrical spine of every data hall.
GV
GE VernovaAmerica's turbine and grid champion — sold out of gas turbines into the 2030s.
HE
Hitachi EnergyThe world's largest transformer maker — the grid's longest lead-time item.
InfineonPower semiconductors from grid to GPU — partner on NVIDIA's 800V architecture.
MH
Mitsubishi Heavy IndustriesThe third member of the gas-turbine oligopoly feeding AI campuses.
MP
Monolithic Power SystemsThe voltage regulators feeding each GPU its thousand amps.
NS
Navitas SemiconductorGaN power chips named into NVIDIA's next-gen power designs.
Rolls-RoyceBackup power today, small modular reactors tomorrow.
SE
Schneider ElectricPower distribution plus cooling (Motivair) — a full data-center electrical stack.
SE
Siemens EnergyGas turbines and grid equipment — order books stretched by AI power demand.
ON
onsemiSilicon-carbide and power chips pushing into data-center supply units.
Kühlung & Thermik
7
AS
AsetekThe liquid-cooling patent pioneer, from gaming PCs to data centers.
BO
BoydThermal engineering at scale: cold plates, loops and heat exchangers.
CS
CoolIT SystemsCold plates and CDUs from the direct-liquid-cooling pioneer.
LI
LiquidStackImmersion-cooling specialist now spanning tanks and CDUs.
MU
MuntersAir-handling and evaporative cooling for hyperscale halls.
SU
SubmerEuropean immersion-cooling maker for dense AI and edge compute.
VE
VertivThe pure-play data-center infrastructure leader: cooling, UPS, busway.
Rechenzentrumsbetreiber
10
AD
Aligned Data CentersHigh-density specialist that raised a record $12B+ equity round in 2025.
 CyrusOneKKR/GIP-owned wholesale developer expanding for AI tenants.
DR
Digital RealtyWholesale data-center REIT with 300+ facilities on six continents.
EQ
EquinixThe interconnection king: 270+ data centers where networks meet.
GH
GDS HoldingsChina's leading carrier-neutral data-center developer.
IM
Iron MountainThe records giant that built a fast-growing data-center arm.
NG
NTT Global Data CentersJapan's giant with one of the world's largest colocation footprints.
QD
QTS Data CentersBlackstone's data-center arm — the largest private development pipeline in the US.
SW
SwitchThe Citadel and other US mega-campuses, taken private by DigitalBridge.
VD
Vantage Data CentersDigitalBridge-backed hyperscale developer building gigawatt campuses.
CyrusOneKKR/GIP-owned wholesale developer expanding for AI tenants.
DR
Digital RealtyWholesale data-center REIT with 300+ facilities on six continents.
EQ
EquinixThe interconnection king: 270+ data centers where networks meet.
GH
GDS HoldingsChina's leading carrier-neutral data-center developer.
IM
Iron MountainThe records giant that built a fast-growing data-center arm.
NG
NTT Global Data CentersJapan's giant with one of the world's largest colocation footprints.
QD
QTS Data CentersBlackstone's data-center arm — the largest private development pipeline in the US.
SW
SwitchThe Citadel and other US mega-campuses, taken private by DigitalBridge.
VD
Vantage Data CentersDigitalBridge-backed hyperscale developer building gigawatt campuses.
Versorgungsunternehmen & Stromerzeugung
20
AE
American Electric PowerOhio's transmission giant handling the New Albany AI corridor.
BT
BWX TechnologiesThe nuclear component manufacturer every reactor program runs through.
CE
Constellation EnergyAmerica's largest nuclear fleet — restarting Three Mile Island for Microsoft.
DE
Dominion EnergyThe utility of Data Center Alley — more AI load than anywhere on Earth.
DE
Duke EnergySoutheast utility signing AI campuses across the Carolinas.
EN
EntergyLouisiana's utility powering Meta's Hyperion with new gas turbines.
HI
Holtec InternationalThe company that did the 'impossible': restarting the Palisades reactor.
KP
Kairos PowerGoogle's SMR partner: molten-salt-cooled reactors, 500 MW by 2035.
NE
NRG EnergyTexas retail-and-generation player building gas plants with GE Vernova for data centers.
NE
NextEra EnergyThe renewables superpower selling speed-to-power to data centers.
NP
NuScale PowerThe only SMR design with US NRC approval — still awaiting its first order build.
OK
OkloFast-reactor startup, long chaired by Sam Altman, targeting data-center power.
 Sempra (Oncor)Owner of Oncor, the Texas wires company fielding a 100+ GW interconnection queue.
SC
Southern CompanyOwner of Vogtle — America's newest big reactors — amid Georgia's data-center boom.
TE
Talen EnergySusquehanna nuclear next to an AWS campus — the original co-location deal.
TE
TerraPowerBill Gates's Natrium reactor, under construction in Wyoming.
 US Department of EnergyThe public sector's compute and power heavyweight: exascale labs, loans, reactors.
VI
VistraTexas's merchant power giant — nuclear, gas and batteries into ERCOT.
WE
WestinghouseThe AP1000 builder positioned for a US large-reactor revival.
XE
X-energyAmazon-backed high-temperature gas reactor developer.
Sempra (Oncor)Owner of Oncor, the Texas wires company fielding a 100+ GW interconnection queue.
SC
Southern CompanyOwner of Vogtle — America's newest big reactors — amid Georgia's data-center boom.
TE
Talen EnergySusquehanna nuclear next to an AWS campus — the original co-location deal.
TE
TerraPowerBill Gates's Natrium reactor, under construction in Wyoming.
US Department of EnergyThe public sector's compute and power heavyweight: exascale labs, loans, reactors.
VI
VistraTexas's merchant power giant — nuclear, gas and batteries into ERCOT.
WE
WestinghouseThe AP1000 builder positioned for a US large-reactor revival.
XE
X-energyAmazon-backed high-temperature gas reactor developer.
Cloud & Hyperscale
7 AlibabaChina's biggest cloud and the maker of Qwen — the world's most-forked open models.
 Amazon Web ServicesThe largest cloud, building custom silicon and gigawatt campuses for Anthropic.
 Google (Alphabet)The only company vertically integrated from TPU silicon to frontier models.
 IBMEnterprise AI (watsonx, Granite) plus the quantum roadmap.
 MicrosoftAzure, the OpenAI alliance, Copilot — and Fairwater-class AI factories.
 OracleThe late-arriving cloud that bet the company on OpenAI and Stargate.
 TencentWeChat's owner: Hunyuan models and China's other hyperscale cloud.
KI-Cloud
8
AD
Applied DigitalNorth Dakota mega-campuses leased to CoreWeave — miner-to-AI conversion story.
CO
CoreWeaveThe crypto-miner turned $20B-contract AI hyperscaler — the defining neocloud.
CR
CrusoeEnergy-first AI builder: from flare-gas computing to constructing Stargate Abilene.
G4
G42The UAE's state-linked AI champion — Microsoft-invested, Cerebras's anchor.
IR
IRENBitcoin miner turned AI cloud with a reported $9.7B Microsoft GPU deal.
LA
LambdaThe developer-facing GPU cloud that landed a multi-billion Microsoft deal.
NE
NebiusThe ex-Yandex AI cloud with a reported $17B+ Microsoft contract.
TA
Together AIOpen-model inference cloud and research shop (FlashAttention lineage).
KI-Labs & Software
33
AL
AI21 LabsIsraeli lab known for the Jamba hybrid Mamba-transformer models.
AN
AnthropicThe safety-focused lab behind Claude — powered by Trainium, TPUs and GPUs at once.
A(
Anysphere (Cursor)Maker of Cursor — the fastest-growing developer product in history (reported).
BA
BaiduChina's search giant: ERNIE models, Apollo Go robotaxis, Kunlun chips.
BF
Black Forest LabsThe Stable Diffusion authors' second act: the FLUX image models.
CO
CohereEnterprise-only models from a transformer-paper co-author.
DA
DatabricksThe data-lakehouse platform where enterprises actually deploy AI.
DE
DeepSeekThe lab that shook the market: frontier results at a fraction of the compute.
EL
ElevenLabsThe voice-AI leader: cloning, dubbing and conversational agents.
FA
Figure AIHumanoid robots with in-house VLA models — a $39B bet on embodied AI.
GD
Google DeepMindFrom AlphaGo to Gemini and AlphaFold — the lab with a Nobel Prize on the shelf.
HF
Hugging FaceThe GitHub of models: two million model repos and the open ecosystem's home.
LA
LG AI ResearchKorea's enterprise lab (EXAONE) and FuriosaAI's anchor customer.
LA
Luma AIDream Machine video and multimodal world-model ambitions — Humain-backed.
 MetaOpen-weights standard-bearer turned superintelligence spender.
MI
MidjourneyThe bootstrapped image lab that never took venture money.
MI
MiniMaxShanghai lab spanning LLMs, video (Hailuo) and companion apps.
MA
Mistral AIEurope's frontier hope — efficient open models, ASML-led funding.
MA
Moonshot AIMaker of Kimi — trillion-parameter open MoE models with agentic focus.
OP
OpenAIMaker of ChatGPT and GPT-5 — and the buyer behind the biggest compute deals ever signed.
PA
PalantirOntology-driven AI deployment for governments and industry.
PE
PerplexityThe answer engine attacking Google head-on — browser and all.
PI
Physical IntelligenceFoundation models for any robot — the π0 lab.
RU
RunwayVideo generation for filmmakers — Gen-4 and Hollywood partnerships.
SS
Safe SuperintelligenceIlya Sutskever's one-product company: superintelligence, safely, nothing else.
SA
Scale AIThe data-labeling giant Meta bought half of for $14.3B.
SA
Stability AIThe company that open-sourced image generation — then nearly collapsed.
SU
SunoText-to-song generation — and the music industry's test case.
 TeslaReal-world AI at automotive scale: FSD, Optimus, and the AI5 chip program.
TM
Thinking Machines LabMira Murati's lab — a record $2B seed and a fine-tuning product (Tinker).
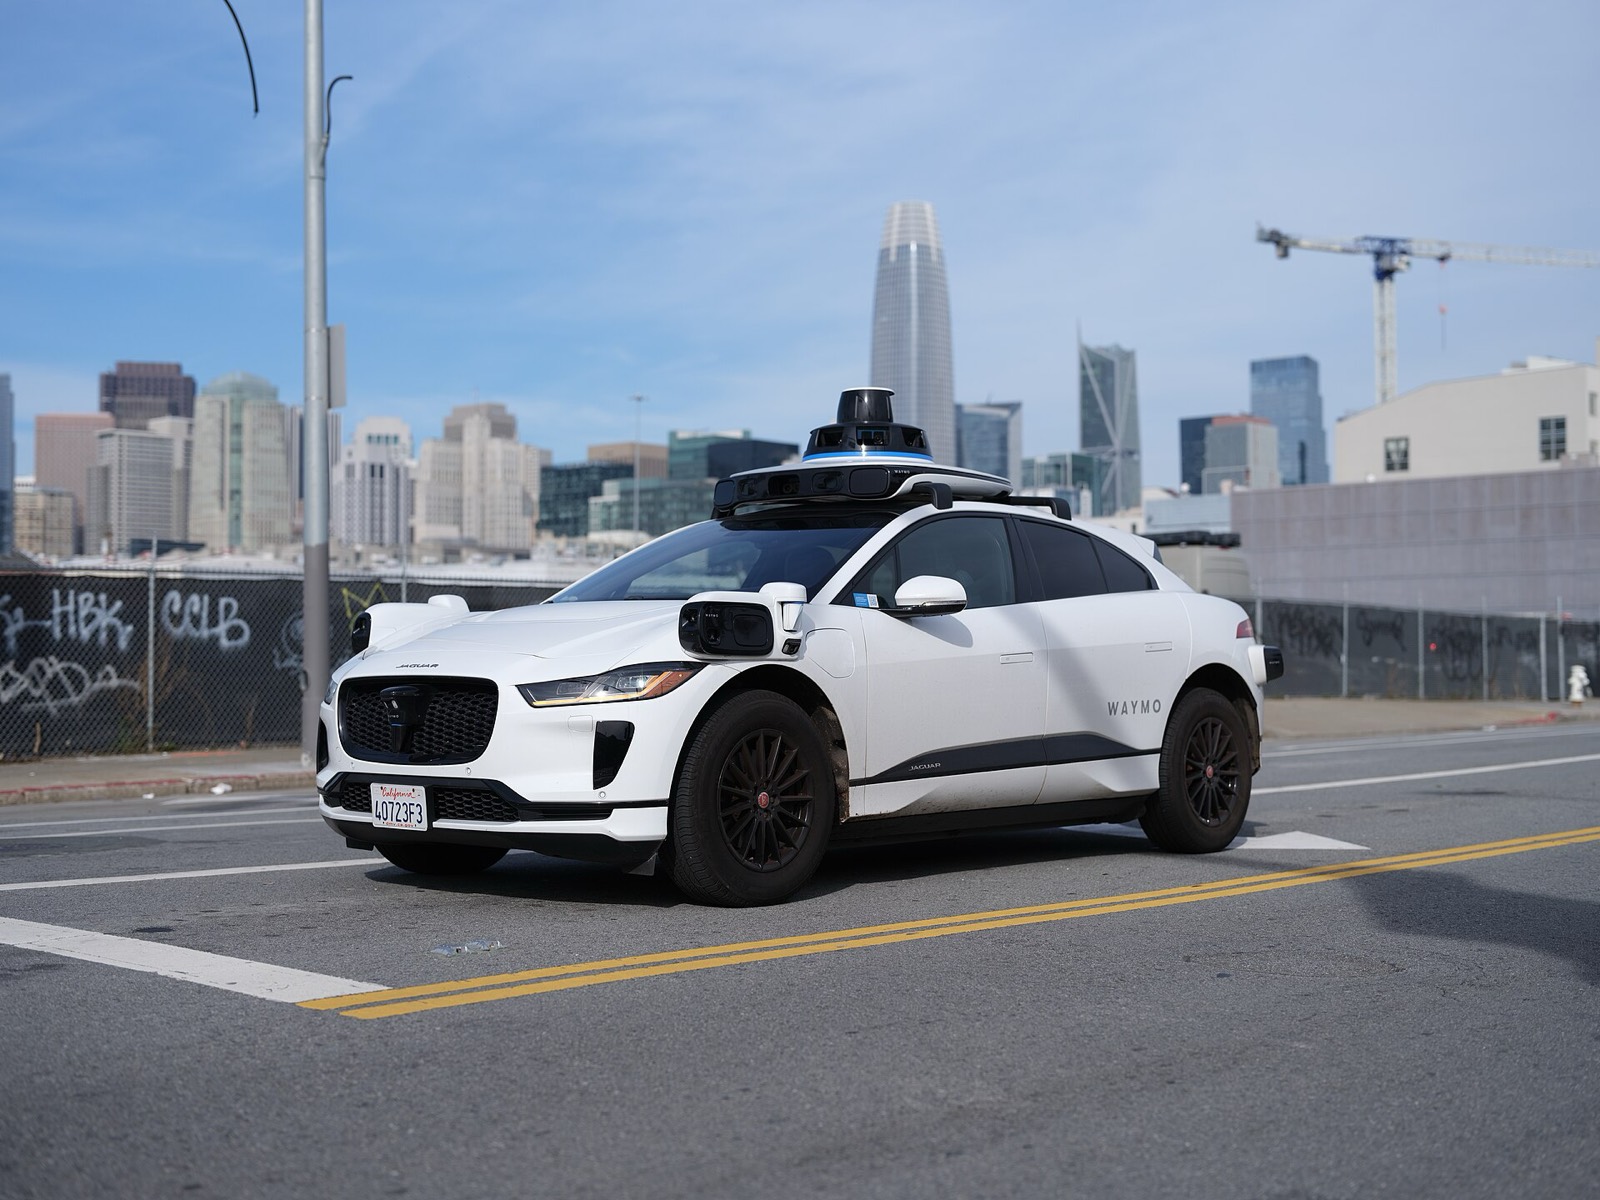 WaymoThe only driverless service operating at real commercial scale.
ZA
Zhipu AI (Z.ai)Tsinghua-born lab behind the GLM open-model line.
XA
xAIElon Musk's lab: Grok models and the fastest data-center build ever seen.
MetaOpen-weights standard-bearer turned superintelligence spender.
MI
MidjourneyThe bootstrapped image lab that never took venture money.
MI
MiniMaxShanghai lab spanning LLMs, video (Hailuo) and companion apps.
MA
Mistral AIEurope's frontier hope — efficient open models, ASML-led funding.
MA
Moonshot AIMaker of Kimi — trillion-parameter open MoE models with agentic focus.
OP
OpenAIMaker of ChatGPT and GPT-5 — and the buyer behind the biggest compute deals ever signed.
PA
PalantirOntology-driven AI deployment for governments and industry.
PE
PerplexityThe answer engine attacking Google head-on — browser and all.
PI
Physical IntelligenceFoundation models for any robot — the π0 lab.
RU
RunwayVideo generation for filmmakers — Gen-4 and Hollywood partnerships.
SS
Safe SuperintelligenceIlya Sutskever's one-product company: superintelligence, safely, nothing else.
SA
Scale AIThe data-labeling giant Meta bought half of for $14.3B.
SA
Stability AIThe company that open-sourced image generation — then nearly collapsed.
SU
SunoText-to-song generation — and the music industry's test case.
TeslaReal-world AI at automotive scale: FSD, Optimus, and the AI5 chip program.
TM
Thinking Machines LabMira Murati's lab — a record $2B seed and a fine-tuning product (Tinker).
WaymoThe only driverless service operating at real commercial scale.
ZA
Zhipu AI (Z.ai)Tsinghua-born lab behind the GLM open-model line.
XA
xAIElon Musk's lab: Grok models and the fastest data-center build ever seen.
Kapital & Investoren
5
BL
BlackstoneThe largest private-capital owner of data centers (QTS) and their power.
BR
BrookfieldOwner of Westinghouse and a global data-center + renewables platform.
KK
KKRCyrusOne's owner and half of a $50B AI-infrastructure alliance.
MG
MGXAbu Dhabi's $100B AI fund — Stargate's sovereign capital.
SG
SoftBank GroupMasayoshi Son's everything-bet on AI: Arm, OpenAI, Stargate, Ampere, Graphcore.
Börsennotierte Unternehmen verlinken auf die Aktien Seite. Herunterladen: companies.csv